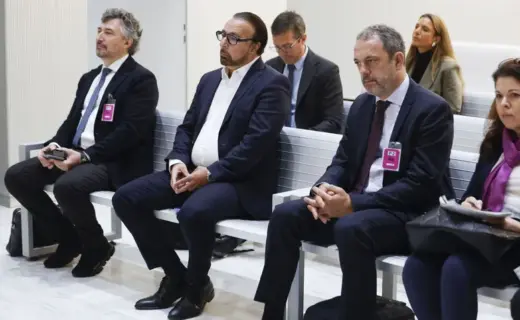

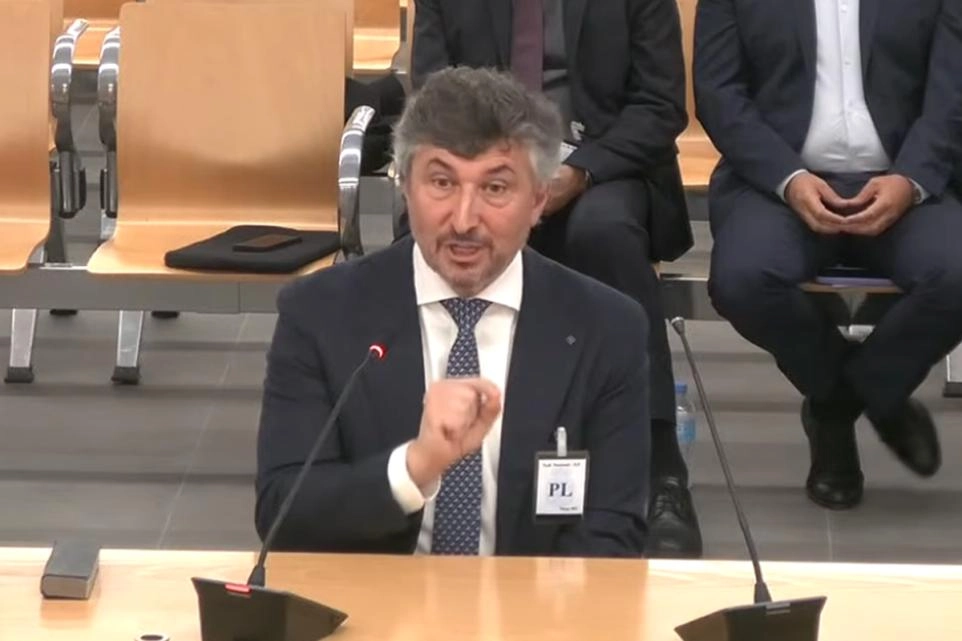
The oral trial in the Caso Líbero tax fraud proceedings involving Granada CF and former club owner Gino Pozzo ended on Tuesday, November 17, 2026, at Spain’s Audiencia Nacional in Madrid. After five court sessions, prosecutors, state lawyers and defence teams delivered their final arguments before the three-judge panel declared the case visto para sentencia, meaning the hearing is closed and the judges are now deliberating on a verdict.
The Gino Pozzo court case centres on roughly €30 million in player-transfer profits generated by Granada CF between 2013 and 2015. Spanish anti-corruption prosecutors are seeking 12-year prison sentences for Pozzo and three co-defendants, alongside multi-million-euro personal fines and a €26.9 million criminal fine against the club.
None of those penalties has been imposed, as the court must first decide whether the alleged offences have been proved.
Prosecution and state lawyers outline tax-evasion claims
Prosecutors allege that profits from Granada’s player sales during the 2013, 2014 and 2015 tax years were routed through companies in Luxembourg and the United Arab Emirates to reduce corporate tax owed in Spain. Central to their argument is Fifteen Securitisation, an entity used in Granada’s player-financing arrangements.
According to the prosecution, the vehicle created the appearance of permanent outside funding while money moved through linked companies before returning to the club, with nominee owners hiding who truly controlled those businesses.
In assigning responsibility, the Anti-Corruption Prosecutor accused Pozzo of designing the structure and choosing the people who ran it. Former Granada president Quique Pina was described as carrying out Pozzo’s instructions and signing the financing contracts, while Jordi Trilles was identified as a tax adviser and Raffaele De La Riva as a financial adviser.
The State Legal Service, which represents the Spanish treasury in court, supported the tax-fraud allegations. Its lawyers pointed to misleading accounting, the use of intermediaries to disguise the ultimate investor and a lack of internal controls at Granada CF.
However, the State Legal Service differed from the Anti-Corruption Prosecutor on Pina’s legal classification, treating him as an alleged necessary cooperator rather than a principal perpetrator. That distinction could influence how the judges weigh individual blame if convictions follow.
Also Read: Barnsley fans plan protest as Bobby Hassell takes interim role
Defence teams reject allegations and seek acquittals
All four individual defendants and Granada CF denied wrongdoing and asked the judges to clear them. Pozzo’s lawyer argued that prosecutors failed to properly trace the money and contended that the Gino Pozzo trial had expanded into a broad attack on his wider influence in football rather than proving specific tax crimes. The defence also noted that Granada’s promotion to Spain’s top division naturally increased player values during that period.
Pina’s defence maintained that the financing was genuine, the contracts were real and the funds were invested directly into players. His lawyer highlighted Granada’s severe financial difficulties at the time and argued that the arrangements were known to both LaLiga and the administrators managing the club’s insolvency process. Defence lawyers for Trilles and De La Riva also requested full acquittals.
Representing Granada CF, the club’s lawyer argued that Granada should not face criminal liability for arrangements from which it allegedly received no profits, describing the club as a victim or instrument rather than a beneficiary.
While acknowledging legal continuity, the defence emphasized that Granada has since changed ownership and management, asking the judges to weigh the tax-compliance controls introduced by newer owners if they find the club guilty.
The club’s representative warned that the requested financial penalties could threaten Granada’s survival, though that argument addressed severe economic strain rather than suggesting a conviction would automatically force the club’s dissolution.
Requested penalties and the disputed tax figure
Alongside the 12-year prison sentences sought for Pozzo, Pina, Trilles and De La Riva, prosecutors requested personal fines of €36.5 million for Pozzo and €27.5 million each for the other three defendants. Against Granada CF as a legal entity, the prosecution is seeking a separate €26.9 million criminal fine, broken down into €1.9 million for 2013, €17 million for 2014 and €8 million for 2015.
Separate from that criminal fine, prosecutors want the defendants and the club to pay roughly €9.44 million in allegedly unpaid corporate tax, plus interest. Public figures for that unpaid tax quota show a small discrepancy. Local newspaper Granada Hoy reported the amount as €9,441,987.11, whereas detailed case schedules and Granada CF’s audited accounts support a figure of €9,441,897.11. Neither the tax claim nor any recorded security deposit represents a final judicial determination of tax liability, which rests strictly with the judges.
Also Read: Can £3m in unsecured borrowing steady AFC Wimbledon’s finances?
Statutory timetable and appeal rules
Under Article 789 of Spain’s Criminal Procedure Act, a court must issue its judgment within five days of the oral trial concluding. Because Article 185 of the Organic Law of the Judiciary excludes weekends and non-working days when counting procedural deadlines, the five working days following Tuesday, November 17 fall on November 18, 19, 20, 23 and 24.
Tuesday, November 24, 2026 is therefore the calculated fifth procedural day for the first-instance ruling in the Pozzo court case, though this is a statutory calculation rather than a guaranteed time for public announcement.
Other articles govern how the judgment is written and how the parties can challenge it. Article 142 of the Criminal Procedure Act sets out the required contents of a criminal ruling, requiring the judges to state the proven facts, record final arguments, explain the legal basis for each defendant’s participation and address any mitigating or aggravating factors.
Once the written judgment is formally notified, Articles 846 ter and 790 give the parties ten working days to appeal to the Audiencia Nacional’s Appeal Chamber. That ten-day period begins only after formal notification of the written decision, not at the end of the trial, and it is paused if any party requests copies of the hearing recordings within three days of notification.